When a Business and Its Property Are Connected

John Acosta
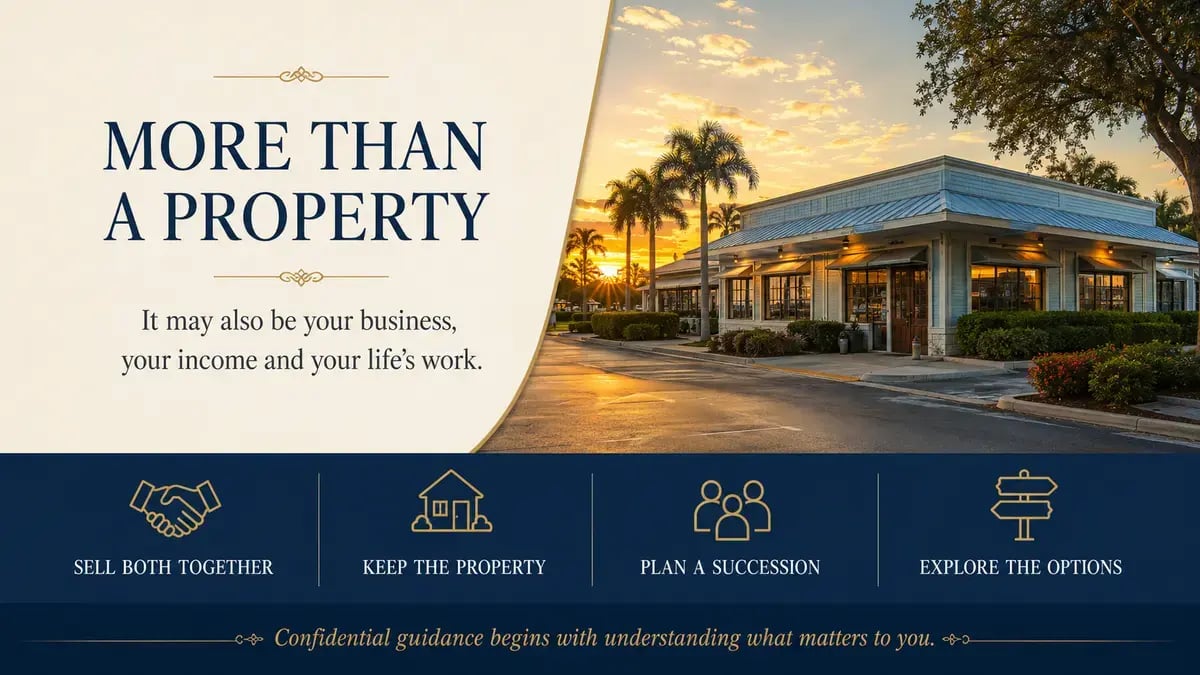
For many Gulf Coast owners, commercial real estate is more than a building or parcel. It may be the home of a family business, a major source of retirement income, an asset intended for the next generation—or all three at once.
That is why the right first question is not always, “What can I sell the property for?” The better question may be, “What outcome do I want for the business, the real estate and the people who depend on both?”
As long-time owners begin thinking about retirement, succession or a change in direction, they may discover that their options are broader than a traditional sale. A thoughtful plan starts by separating the decisions, understanding how they affect one another and assembling the right professionals before going to market.
Why the Business and the Real Estate Need Separate Attention
An operating business and the property it occupies can create value in different ways.
The real estate may be evaluated through location, condition, zoning, market rents, operating expenses, net operating income and comparable sales. The business may be evaluated through normalized cash flow, equipment, inventory, customer concentration, owner dependence, transferable systems and goodwill.
Those values can support one another, but they are not automatically the same. A strong business does not always occupy the best long-term property, and a valuable property does not always guarantee a transferable business. Understanding both sides helps an owner avoid making one decision that unintentionally weakens the other.
Five Possible Paths for an Owner
There is no single structure that fits every owner. The right path depends on timing, income needs, family plans, business performance, the property itself and the availability of qualified buyers or operators.
1. Sell the Business and the Real Estate Together
Selling both may appeal to a buyer who wants a complete operating location and to an owner who wants a cleaner exit. It can also reduce uncertainty about whether a new business owner will have a suitable place to operate.
The challenge is that the buyer must be comfortable with two different investments at the same time. The business needs to support its purchase terms while the real estate must also make sense at its own value. Financing, valuation and the allocation of the purchase price can therefore become more involved.
2. Sell the Business and Keep the Property
Some owners sell the operating business but retain the real estate and lease it to the new operator. This may preserve rental income and allow the owner to keep a long-term property asset.
For this structure to work, the lease should be sustainable for the business and appropriate for the property. Lease length, renewal options, maintenance responsibilities, insurance, taxes and future sale rights deserve careful review. The strength of the new operator also matters because the property owner may become dependent on that tenant’s performance.
3. Sell the Property and Continue or Relocate the Business
An owner may choose to unlock equity from the real estate while keeping the business. That could involve relocating the operation, leasing back the property for a period or selling a location that is no longer the best fit.
This path requires a realistic review of relocation costs, customer impact, licensing, zoning, equipment needs and business interruption. A sale-leaseback may also be considered in some situations, but the rent and lease terms must work for both the buyer and the operating business.
4. Keep Both and Plan for New Management or Succession
Not every transition requires a sale. An owner may retain the business and real estate while transferring daily responsibility to a family member, key employee or professional operator.
This approach can provide continuity, but it depends on more than identifying a successor. The business should have documented systems, reliable financial records, clear authority and a transition timeline. The real estate ownership and lease arrangements should also be addressed so future decision-makers understand their rights and responsibilities.
5. Use a Phased Transition
Some owners prefer to move in stages. An owner might first strengthen financial reporting, address deferred property maintenance, formalize a lease, reduce owner dependence and then pursue a sale later.
Depending on the circumstances and professional advice, a phased plan might also include seller financing, an earnout, a management transition or separate closing dates. These structures can provide flexibility, but they also introduce risk and should be reviewed carefully by legal, tax and financial professionals.
Two Valuation Conversations, Not One
Before choosing a path, owners should understand the questions that a serious buyer, lender or advisor is likely to ask.
The Real Estate Conversation
For an owner-occupied or investment property, the discussion may include:
- Current condition and deferred maintenance
- Zoning, permitted use and potential alternative uses
- Actual rent and market rent
- Operating expenses and net operating income
- Comparable sales and replacement cost
- Insurance, flood exposure and other property-specific risks
- Debt service and the cash a buyer may need at closing
- Potential improvements that could increase income or marketability
The Business Conversation
For the operating business, the discussion may include:
- Several years of tax returns and financial statements
- Normalized seller’s discretionary earnings or EBITDA, when appropriate
- Equipment, inventory and working-capital needs
- Customer concentration and recurring revenue
- Licenses, contracts and transferable relationships
- Dependence on the current owner
- Staffing and management depth
- Competitive position, growth opportunities and downside risks
The goal is not to force both assets into one number. It is to understand what creates value, what could reduce value and what a buyer would need to operate successfully after closing.
Information Worth Organizing Early
Owners do not need to decide everything before beginning a conversation, but organized information can make the available options much easier to compare.
A useful starting file may include:
- Property deed, survey, title information and existing loan documents
- Current leases, amendments and tenant records
- Property-tax, insurance, utility and maintenance expenses
- Capital improvements and known repair needs
- Zoning, licenses, permits and environmental records
- Three to five years of business tax returns and financial statements
- Current year-to-date profit-and-loss statement and balance sheet
- Equipment, inventory and asset lists
- Customer, supplier and employee concentration information
- Ownership documents, operating agreements and succession plans
- The owner’s preferred timeline, income needs and desired future involvement
Confidentiality matters. Sensitive business information should be shared through an organized process and, when appropriate, under a confidentiality agreement prepared or reviewed by counsel.
Tax and Legal Structure Can Change the Result
A transaction involving a business and real estate is rarely treated as the sale of one simple asset.
The Internal Revenue Service explains that the assets of a business are generally classified and evaluated separately when determining gain or loss. When a group of assets constituting a trade or business is sold, both parties may also have reporting and purchase-price-allocation responsibilities, including Form 8594 in applicable transactions.
A Section 1031 exchange may be worth discussing when qualifying real property held for business or investment is involved. However, current federal rules generally limit Section 1031 treatment to qualifying real property—not the business’s equipment, inventory, goodwill or other intangible assets.
Timing and structure are critical, so an owner should consult qualified tax, legal and exchange professionals before taking action.
The final plan may require coordination among a real estate advisor, attorney, CPA, lender, appraiser, qualified intermediary and experienced business intermediary. Each professional addresses a different part of the decision.
A Real-Estate-First Approach to a Broader Decision
My role is to help owners frame the real estate decision, identify the right questions, assemble information and coordinate with attorneys, CPAs, lenders, appraisers and experienced business intermediaries when needed.
That approach keeps the property strategy connected to the owner’s larger goals without pretending that every situation is the same.
For one owner, success may mean selling both assets and retiring. For another, it may mean keeping the property as an income-producing investment. For a third, it may mean preparing now so a family member or new operator can take over later.
The first conversation does not have to begin with a listing. It can begin with understanding what matters to you, what you own and which options deserve a closer look.
If you own a business and commercial property in Sarasota, Manatee or Tampa Bay and are beginning to consider what comes next, contact John Acosta for a confidential initial conversation.
Sources and Further Reading
U.S. Small Business Administration — Manage Your Business
https://www.sba.gov/counseling/manage-your-business/
Internal Revenue Service — Sale of a Business
https://www.irs.gov/businesses/small-businesses-self-employed/sale-of-a-business
Internal Revenue Service — About Form 8594
https://www.irs.gov/forms-pubs/about-form-8594
Internal Revenue Service — Like-Kind Exchanges: Real Estate Tax Tips
https://www.irs.gov/businesses/small-businesses-self-employed/like-kind-exchanges-real-estate-tax-tips
This article is for general informational purposes only and is not legal, tax, accounting, valuation or investment advice. Every transaction is different. Consult qualified professionals regarding your particular circumstances.
